“Assistance is free money with no catch.”
There’s Always A Tradeoff
It might be a second loan, a forgiveness period, or a slightly higher rate. Assistance can still be the right move, but you should see the cost before you choose it.
The down payment is the biggest thing standing between most buyers and a home. Assistance programs can cover it, sometimes all of it. I’ll show you which ones you qualify for and the tradeoff that comes with each.
Down payment assistance is money from a state program, local program, or lender that helps cover your down payment and sometimes closing costs. It comes as a grant you never repay, a loan that's forgiven over time, or a loan you repay when you sell or refinance.
Assistance comes from different places. The Louisiana Housing Corporation runs statewide programs, some parishes and cities have their own, and some lenders offer assistance tied to their loans. Each one sets its own rules on income, purchase price, credit score, and whether you need to take a homebuyer education course.
Most assistance is paired with a regular first mortgage like FHA or conventional. The assistance itself is often a second loan with its own terms, so it's important to know whether it's forgiven over time, due when you sell or refinance, or repaid monthly.
Down payment assistance makes the most sense when you can afford the monthly payment but haven't been able to save the cash to get in. If your budget works and the only thing standing between you and a home is the money at closing, assistance can close that gap.
It's also useful when you'd rather keep your savings as a cushion after you move in. A new home always comes with surprises, and walking in with money in the bank can matter more than putting every dollar into the down payment.
The trade off is that assistance isn't always free. Some programs come with a slightly higher rate, a second lien on your home, or a balance due when you sell or refinance. If you have the savings, compare your payment with and without assistance before you decide.
“Assistance is free money with no catch.”
It might be a second loan, a forgiveness period, or a slightly higher rate. Assistance can still be the right move, but you should see the cost before you choose it.
“It’s only for first time buyers.”
LHC’s Market Rate GNMA program is open to first time and repeat buyers. Others are first time only.
“I make too much to qualify.”
Some programs have income limits and some don’t. Don’t rule yourself out until someone checks your household against each one.
“Assistance” can mean very different things. Here’s what each one costs you down the road.
Programs open, close, and change as funding moves, so we check what’s available the day you apply.
Louisiana Housing Corporation’s program pairs an FHA, VA, or USDA loan with assistance of up to 4% of the loan amount. It’s open to first time and repeat buyers, usually with about a 640 score.
LHC’s bond programs are built for first time buyers under income limits, and can offer larger assistance than the market rate program.
Local programs come and go with funding. When one is open in your area, we’ll tell you if you can use it.
Some of the lenders we work with offer their own assistance and grant programs. As a broker, we can shop those for you too.
Sometimes the best assistance is not needing it. VA and USDA loans have no down payment at all.
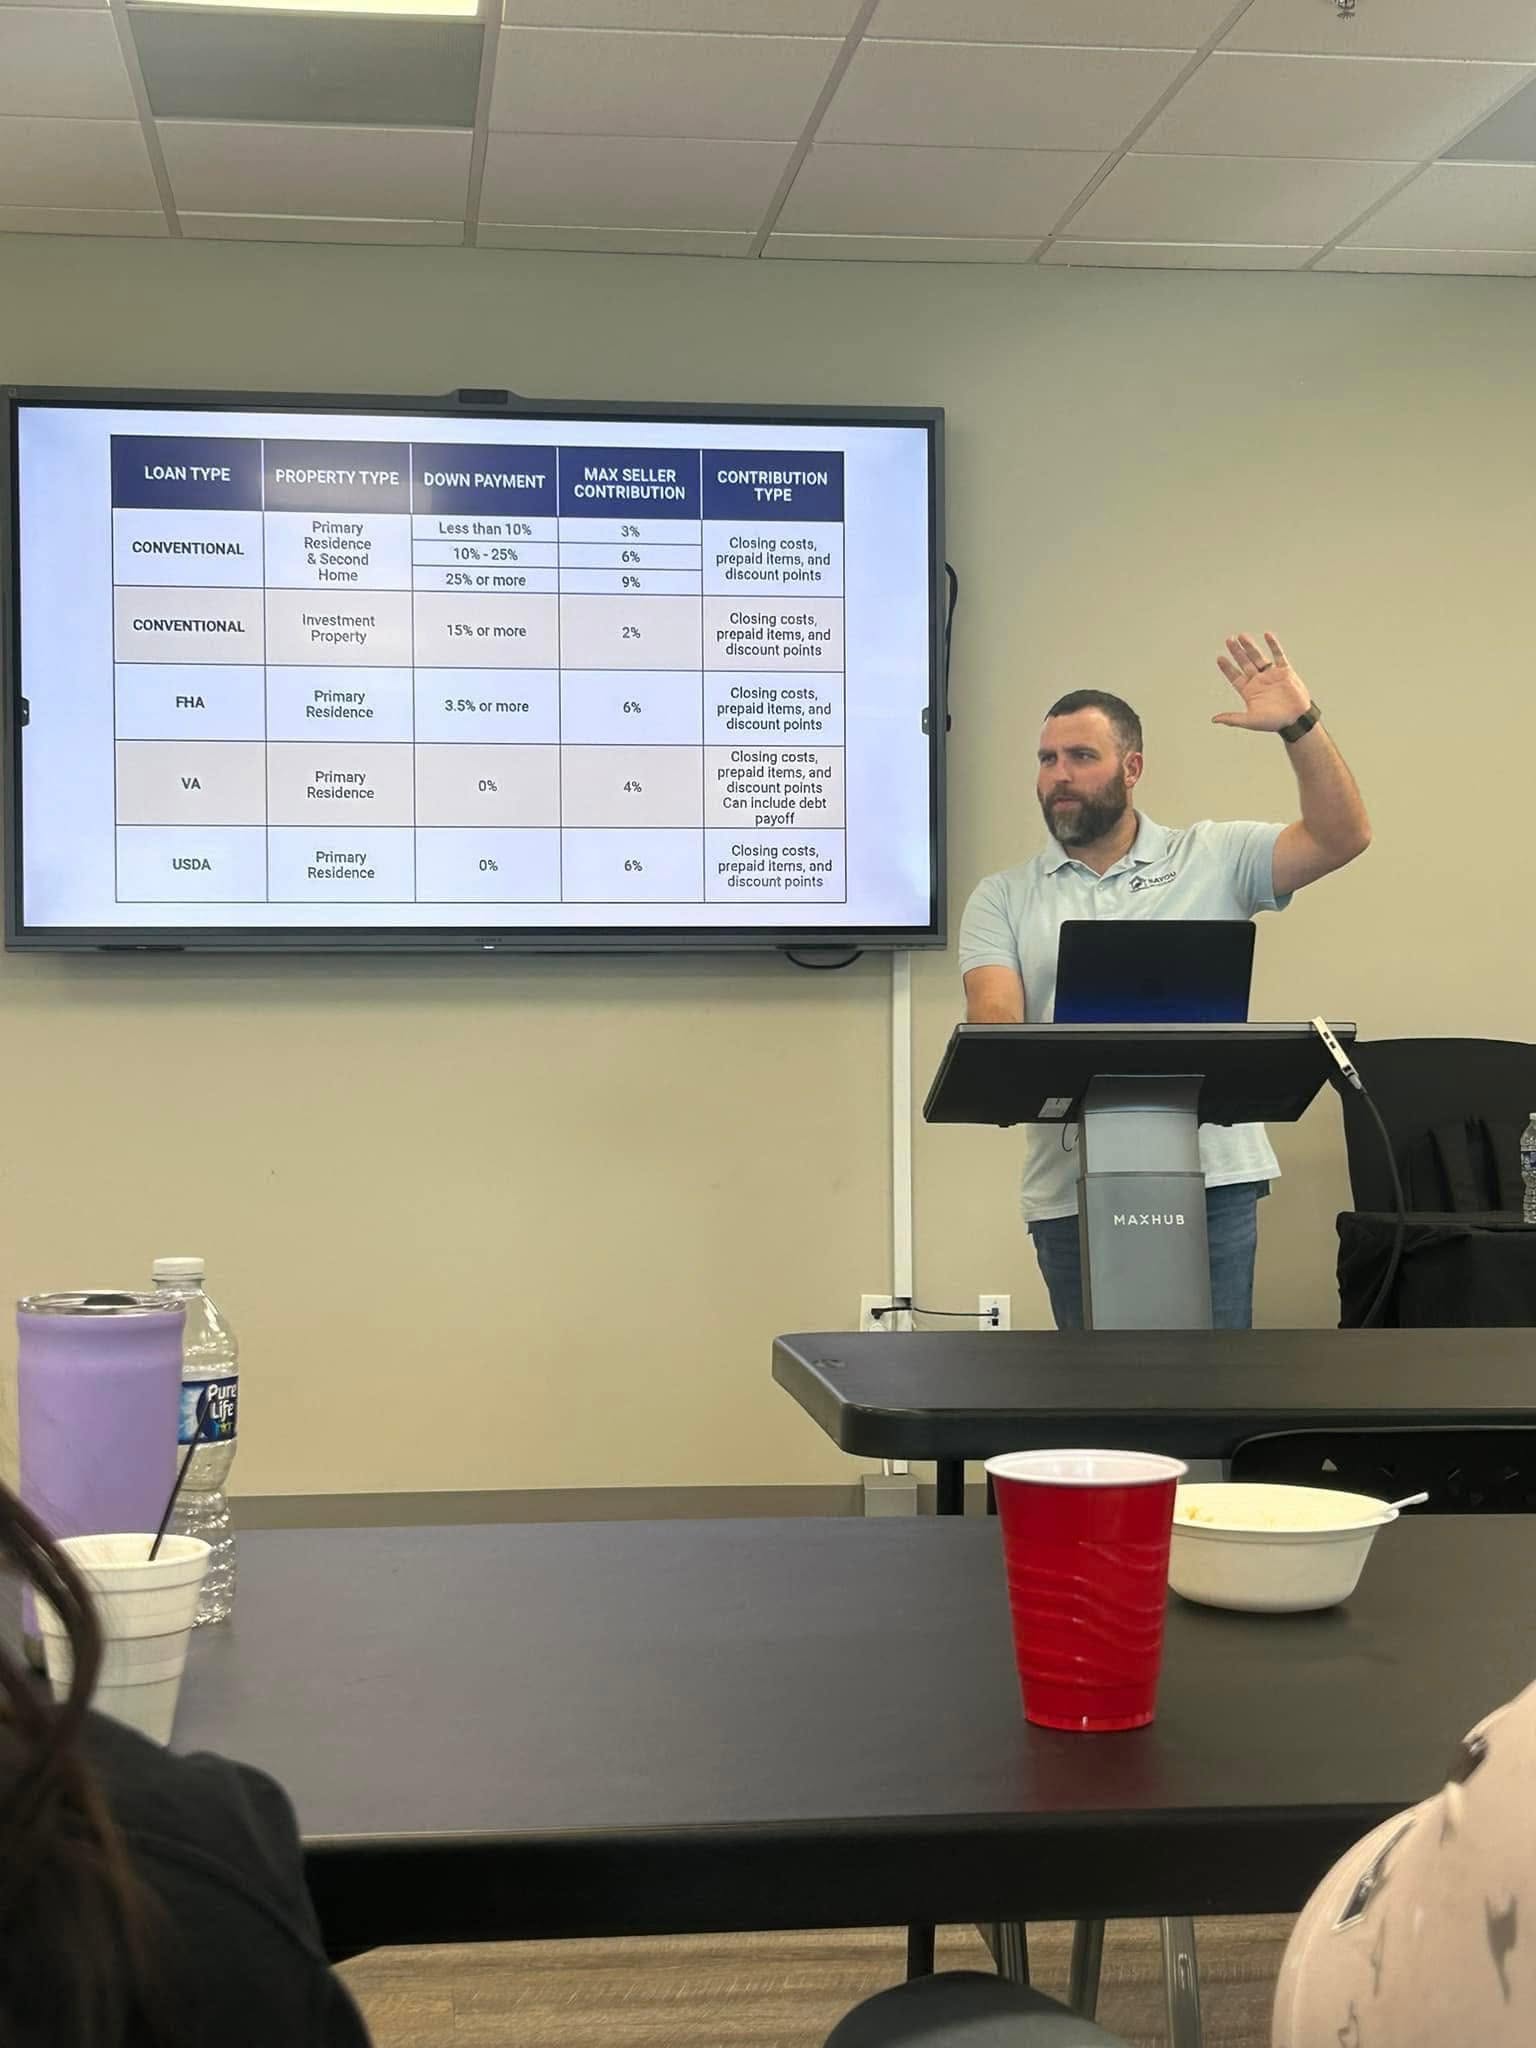
Documented gifts from family and seller paid closing costs can be stacked with assistance to bring your cash to close down further.
Handle these before you start touring homes.
Most programs want a 620 to 640 score. Paying every bill on time for 12 months makes the biggest difference.
Programs with income limits look at household size and income. Know your numbers before you apply.
Many programs require homebuyer education before closing. Getting it done early keeps it from holding up your deal.
Compare the cost of the assistance with the cost of waiting to save. Both have a price.
Here’s exactly what happens after you reach out.
Tell us the price range you’re shopping, your credit range, and how much you have saved. We start with a soft credit check, so your score isn’t touched.
Start My Pre-ApprovalSend your pay stubs, W2s, and bank statements. We compare your loan options side by side and send a letter with your max price to hand your Realtor.
Start My Pre-ApprovalOnce you’re under contract, we order the appraisal, work with title, and take your file through underwriting to closing day.
Start My Pre-Approval

Down payment assistance is money from a state program, local program, or lender that helps cover your down payment and sometimes closing costs. It comes as a grant you never repay, a loan that's forgiven over time, or a loan you repay when you sell or refinance.
Yes. Louisiana Housing Corporation runs statewide programs that Lake Charles buyers can use, there are local and parish programs that open and close as funding allows, and some of our lenders offer their own assistance programs. We check which ones you qualify for when you apply.
Most programs want a 620 to 640 score. If you're under that, you'll likely need to bring your own 3.5% down on an FHA loan, or work on your score first. Late payments in the last 12 months can hurt too.
Not always. Some programs, like Louisiana Housing Corporation's Market Rate GNMA program, are open to first time and repeat buyers. Others are only for first time buyers, which usually means you haven't owned a home in three years, and some are stricter.
Sometimes, but there's always a tradeoff. Some assistance is a grant you never repay. Some is a second loan that's forgiven if you stay in the home long enough, or repaid when you sell or refinance. Some programs come with a slightly higher rate. I'll show you the tradeoff before you choose.
Most assistance pairs with an FHA loan. Some programs also work with VA, USDA, or conventional loans. VA and USDA already have no down payment, so assistance on those usually goes toward closing costs.
Many programs have them, and they vary by program, parish, and household size. Some have no income limit at all. We check your household against each program's limit.
Many assistance programs require a homebuyer education course before closing. My free first time buyer class is a good place to start learning, and we'll tell you if your program requires a specific course.
It depends on the tradeoff and how long saving would take. While you save, prices and rent keep going up. Put both side by side: buying now with assistance against waiting to save, then decide.
Often, yes. Many programs can be used for closing costs as well as the down payment, and you can still ask the seller to cover closing costs on top of the assistance.
Assistance works on top of a first mortgage. These are the loans we’ll compare for you.
The loan most assistance programs pair with. 3.5% down with a 580 score.
Learn More Buy$0 down and no monthly mortgage insurance for veterans. No assistance needed for the down payment.
Learn More Buy$0 down for homes in eligible areas outside the city.
Learn More BuyEvery program that can get you into your first home, compared side by side.
Learn More Buy3% down for first time buyers, with PMI that cancels at 20% equity.
Learn More LearnA live class on Zoom on Tuesdays that walks you through how buying actually works.
Learn MoreFifteen minutes gets you a real number instead of a guess, and the soft credit check costs your score nothing.
Real Closings
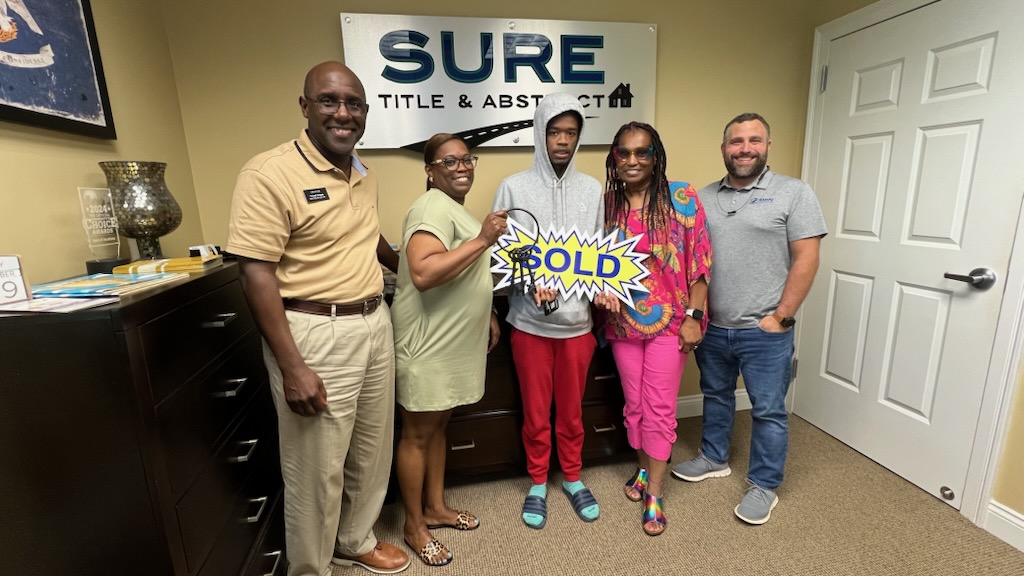
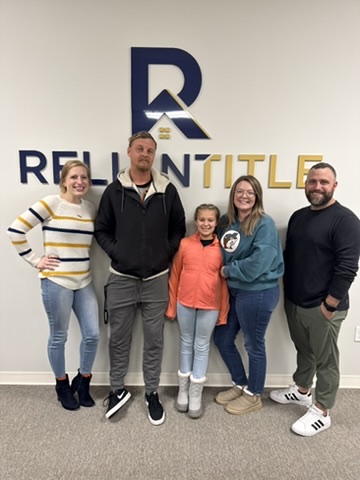
Real families we have helped get from pre-approval to keys in hand.
Pick one and I'll match you to the right loan, the real numbers, and the next step. Takes about 60 seconds — no credit pull, no obligation.