Most people go into this assuming they’re supposed to already understand it. You’re not. I’ll walk you through every number until you could explain it back to me, and you’ll never sign anything you don’t understand.
Average market rates by loan type, with how each has moved over the last 7 and 30 days. Your actual rate depends on your credit score, down payment, and loan details. See all of today’s rates.
Average market rates based on mortgage market index data. Not a commitment to lend and not an offer of credit.
Banks and retail lenders can only offer you what they have. As a mortgage broker, I shop your loan across multiple wholesale lenders, comparing programs, rates, and fees to find what actually fits your situation. That difference shows up in your monthly payment, closing costs, and how long you pay PMI.
Every program we offer in Lake Charles and Southwest Louisiana, grouped by what you’re trying to do. Pick one to see who it’s for, what it takes to qualify, and what it costs.
Programs for buyers, from your first home to your next one.
3.5% down with credit from 580.
Learn More
$0 down and no monthly mortgage insurance.
Learn More
$0 down in eligible areas.
Learn More
3% to 5% down, and insurance that comes off.
Learn More
Every way to buy your first home.
Learn More
Help with your down payment and closing costs.
Learn More
Know your price before you shop.
Learn More
Compare every purchase loan side by side.
Learn More
A place of your own away from home.
Learn MoreHow long you pay and whether your rate can change.
Lower your rate, change your term, or take cash out.
Lower your rate or drop mortgage insurance.
Learn More
Turn your equity into cash.
Learn More
Lower your FHA rate with less paperwork.
Learn More
The simplest refinance for VA loans.
Learn More
Save $50 a month or more, no appraisal.
Learn MoreUse what your home is worth without starting over.
Loans that qualify you on more than a tax return.
Buying a home in Lake Charles comes down to six steps. Most buyers here finance with FHA, VA, conventional, or USDA loans, and on a typical $210,000 home, many put down somewhere between nothing and about $10,500.
Before you look at homes, find out what you can borrow and what the payment will be. Sellers expect a pre-approval letter with every offer.
Compare FHA, VA, conventional, and USDA side by side. The right one depends on your credit, savings, and service history, and it changes how much cash you need.
A local agent can pull recent sales so you know what a home is really worth, from older homes near downtown to newer subdivisions in south Lake Charles, Moss Bluff, and Sulphur.
Send your pre-approval letter with the offer. You can also ask the seller to pay part of your closing costs. FHA allows up to 6% of the price.
Get a home inspection so you know the condition before you commit. We order the appraisal. Get homeowners insurance quotes early, because insurance is a big part of the payment in Southwest Louisiana.
Sign at the title company and get your keys. Then apply for the homestead exemption with your parish assessor to lower your property taxes.
A pre-approval is a lender's review of your income, credit, debts, and savings that shows how much you can borrow. It's different from a prequalification, which is just an estimate based on what you tell us. Your pre-approval letter is what you send with an offer.
Once you’re pre-approved, hold off on new credit cards, car loans, job changes, or large cash moves until you close. Any of those can change your approval.
For most programs, you count as a first time home buyer if you haven't owned a home in the past three years. Most first time buyers in Southwest Louisiana don't need 20% down. Here's the minimum down payment on a $210,000 home, close to the typical Lake Charles value.
Down payment only. Home value data: Zillow Home Value Index, June 2026.
If you have the income for the payment but not the savings, down payment assistance can cover part or all of what you need at closing. Statewide programs through the Louisiana Housing Corporation, plus some lender programs, pair with FHA or conventional loans. Many require a short homebuyer education course, and each one has its own income, price, and credit limits.
Closing costs are separate from the down payment, but they don’t all have to come from you. The seller can pay part of them, and family can gift money toward your down payment. See the full first time home buyer guide and down payment assistance guide.
If you already own a home, a refinance can lower your rate, drop your mortgage insurance, shorten your term, or turn equity into cash. Here's how to decide if it makes sense.
Find your rate, your balance, your loan type, and how many years you have left. Those decide which refinance options are open to you.
Divide the cost to refinance by your monthly savings. If it costs $4,000 and saves $200 a month, you break even in 20 months.
A rate and term refinance lowers your rate or changes your term. FHA, VA, and USDA loans can often use a streamline with less paperwork. If you need cash and your current rate is low, compare a cash out refinance with a HELOC.
We order the appraisal if one is needed, work with title, and take your file through underwriting to closing.
The whole application runs on your phone. Snap photos of your documents, connect your bank, and you’re done. It reaches me the moment you submit it.
Pick one and we’ll start with a soft credit check.
Buy A Home Start Refinance My Home Start Finance An Investment Property Start Prefer to talk first? Call 337-476-2623 or book a call.Here’s exactly what happens after you reach out.
Tell us the price range you’re shopping, your credit range, and how much you have saved. We start with a soft credit check, so your score isn’t touched.
Start My Pre-ApprovalSend your pay stubs, W2s, and bank statements. We compare your loan options side by side and send a letter with your max price to hand your Realtor.
Start My Pre-ApprovalOnce you’re under contract, we order the appraisal, work with title, and take your file through underwriting to closing day.
Start My Pre-Approval
Channing Moore is a licensed mortgage broker, which means we work for you, not a lender. We don’t have products to push or quotas to hit. We have one job: find the loan that makes the most sense for your situation and get you to the closing table.
My goal is simple. Help every family understand their real options, find the best rate, and feel confident about one of the biggest financial decisions they’ll ever make. That’s it.Channing Moore, Owner, The Moore Mortgage Team, NMLS #1235512
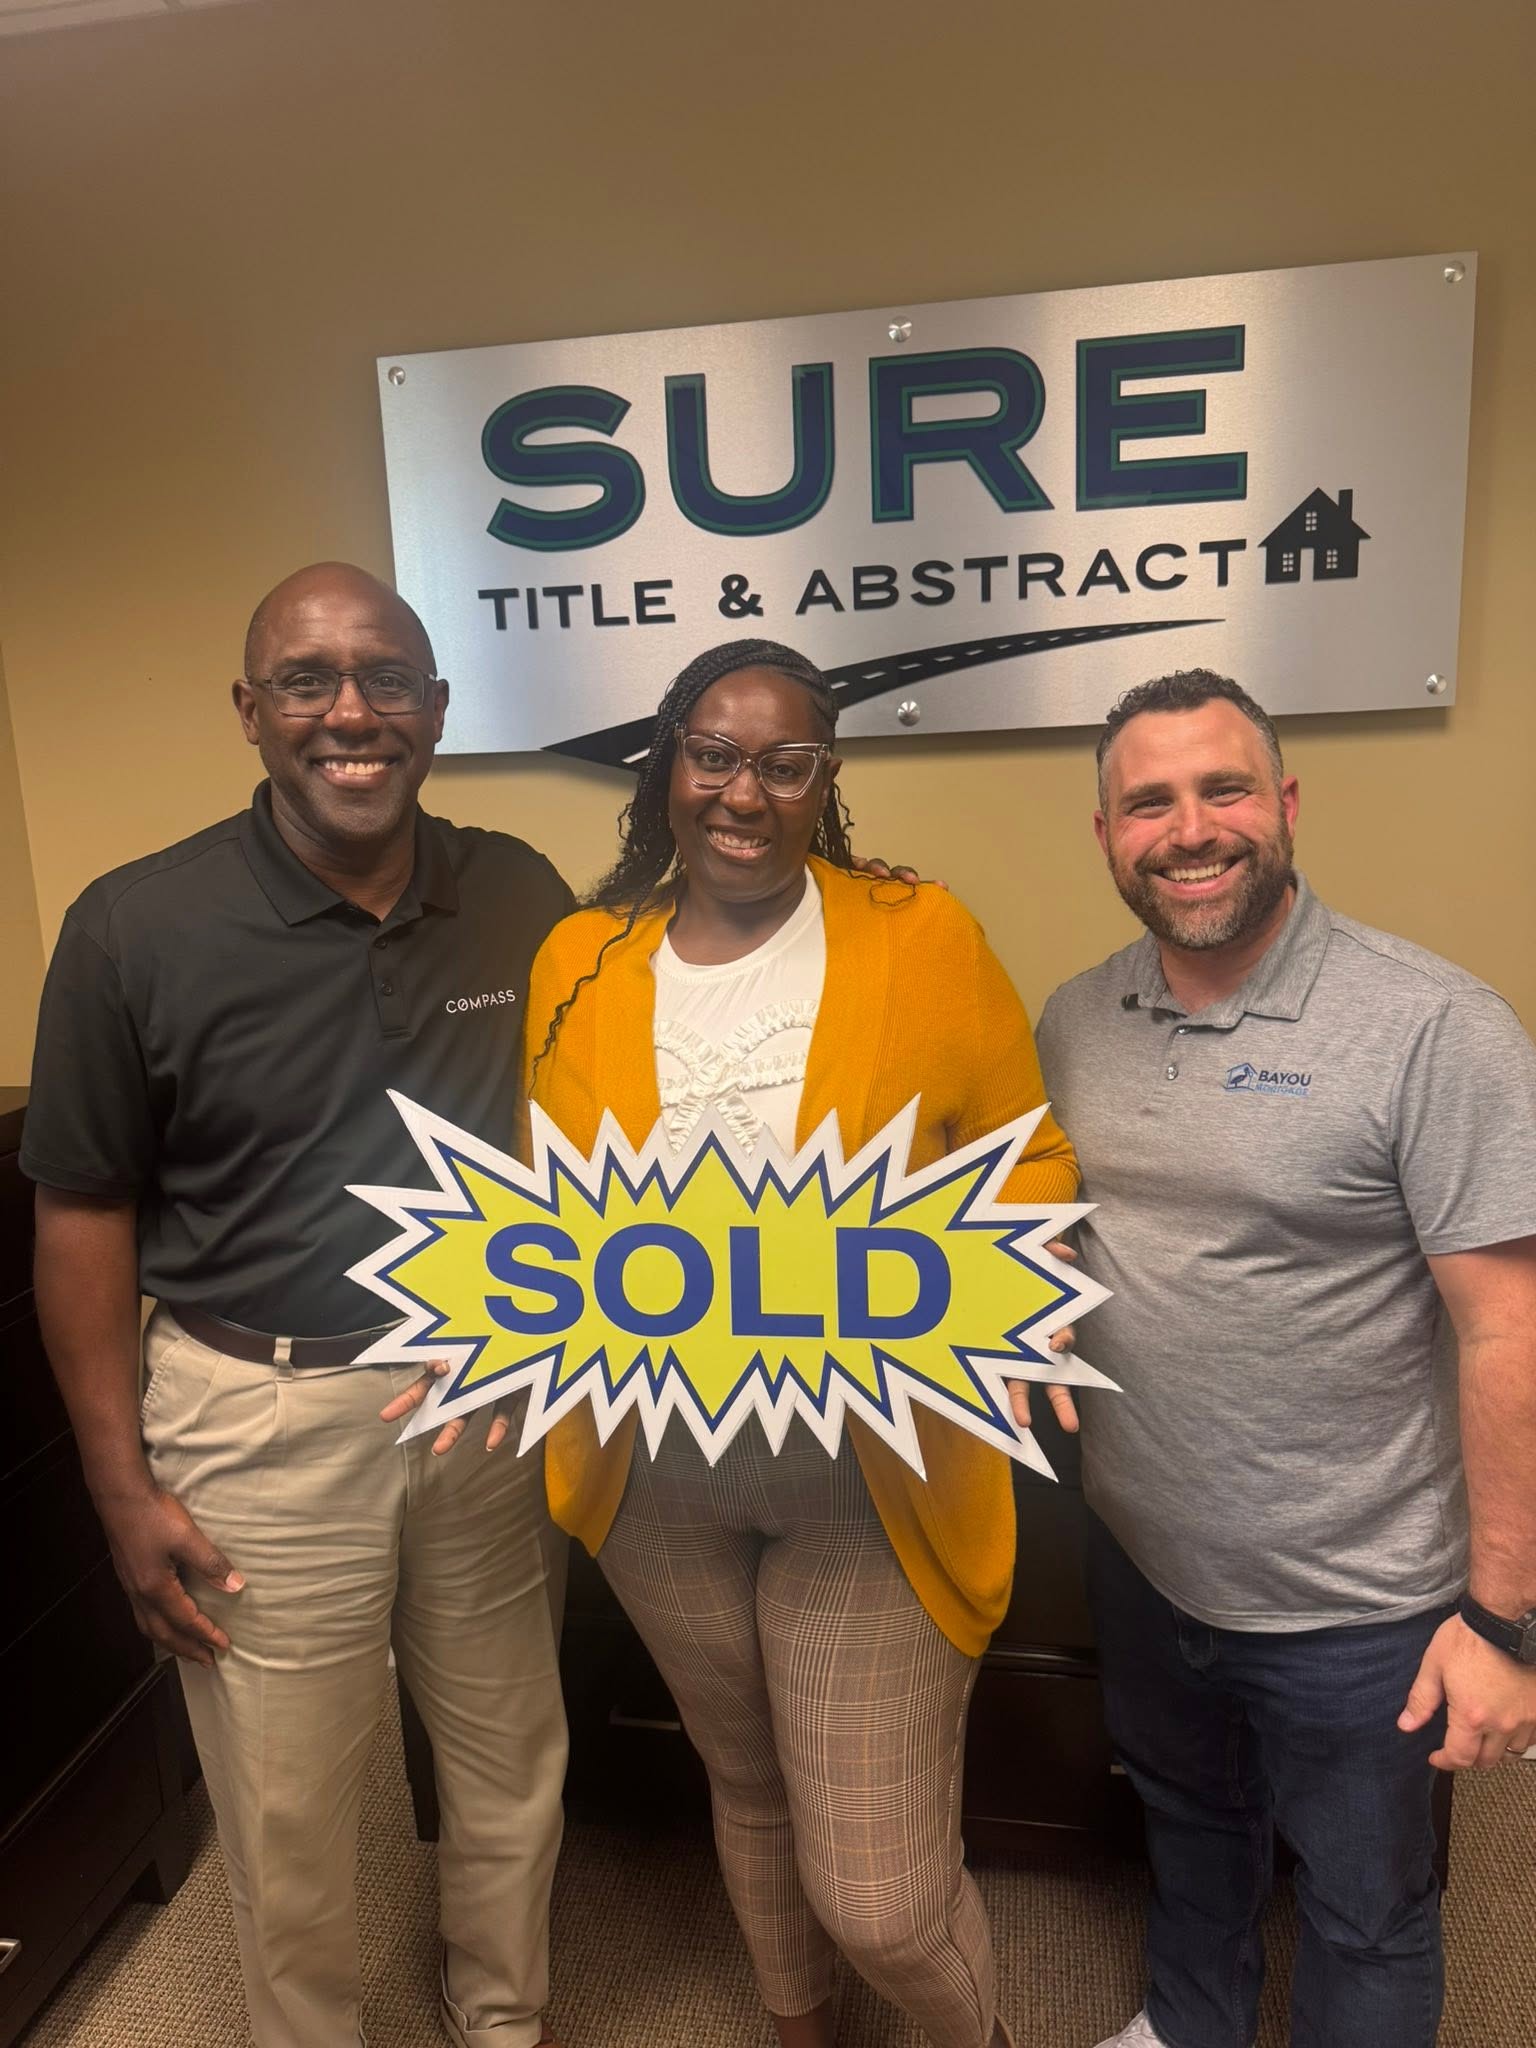
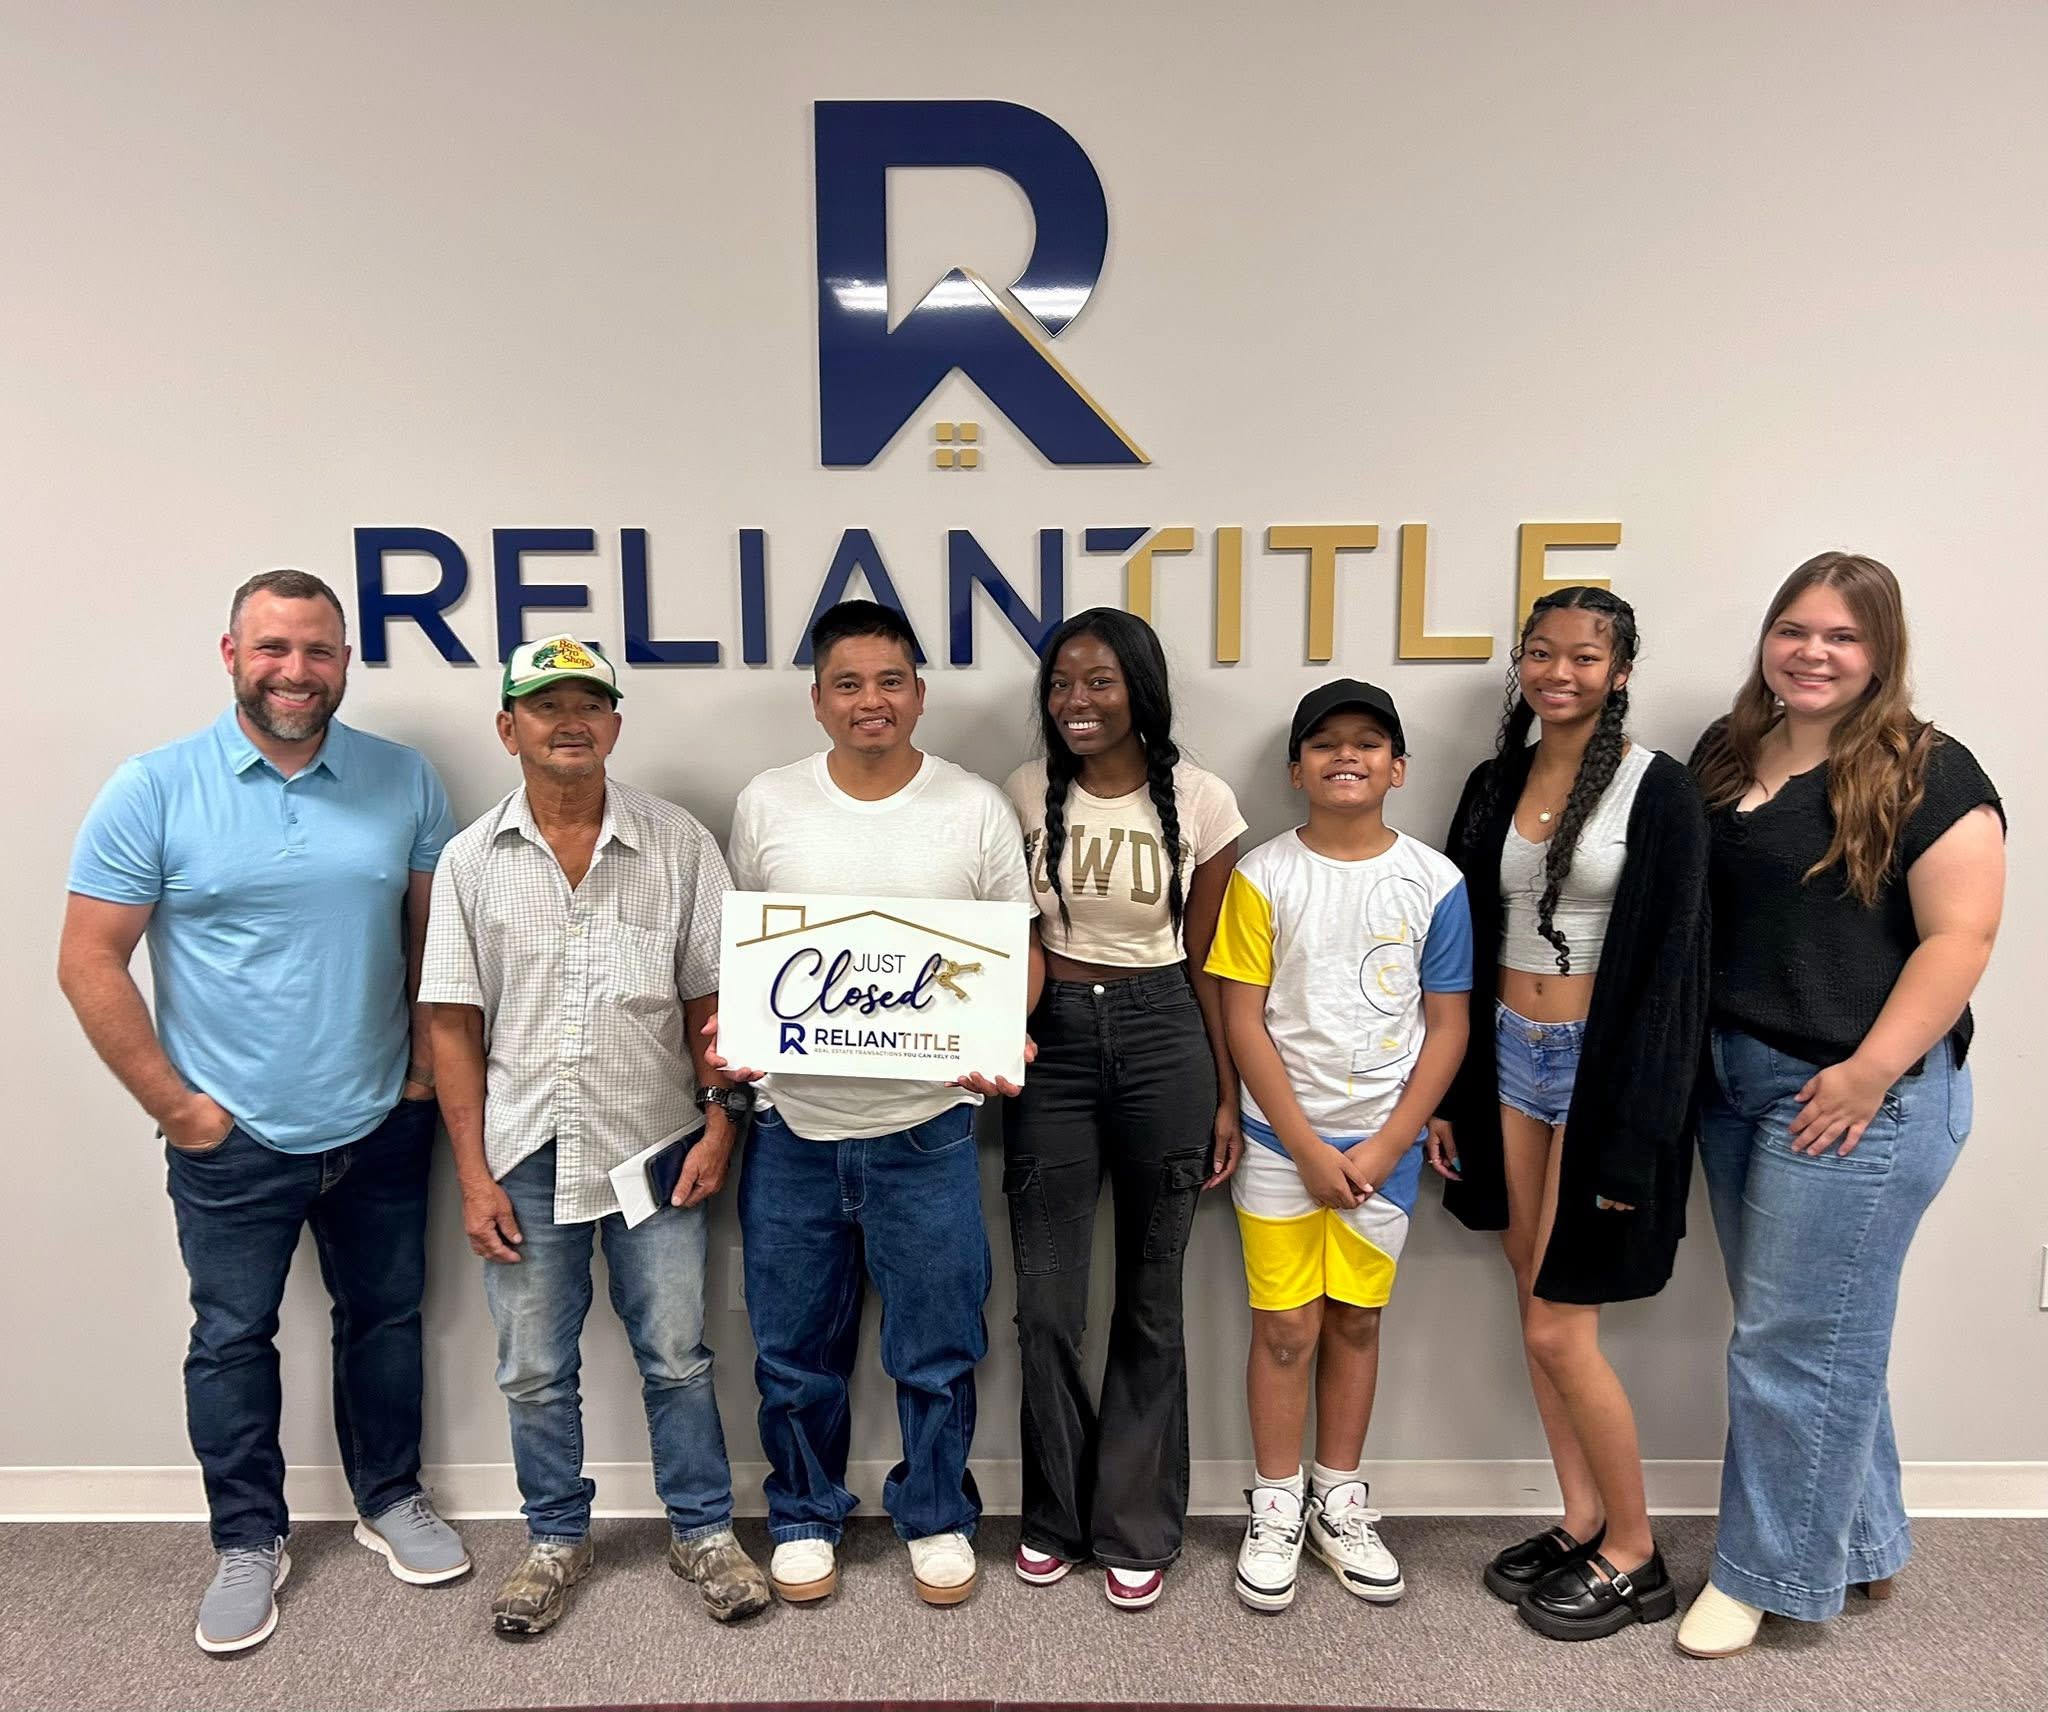
Real families we’ve helped get from pre-approval to keys in hand.
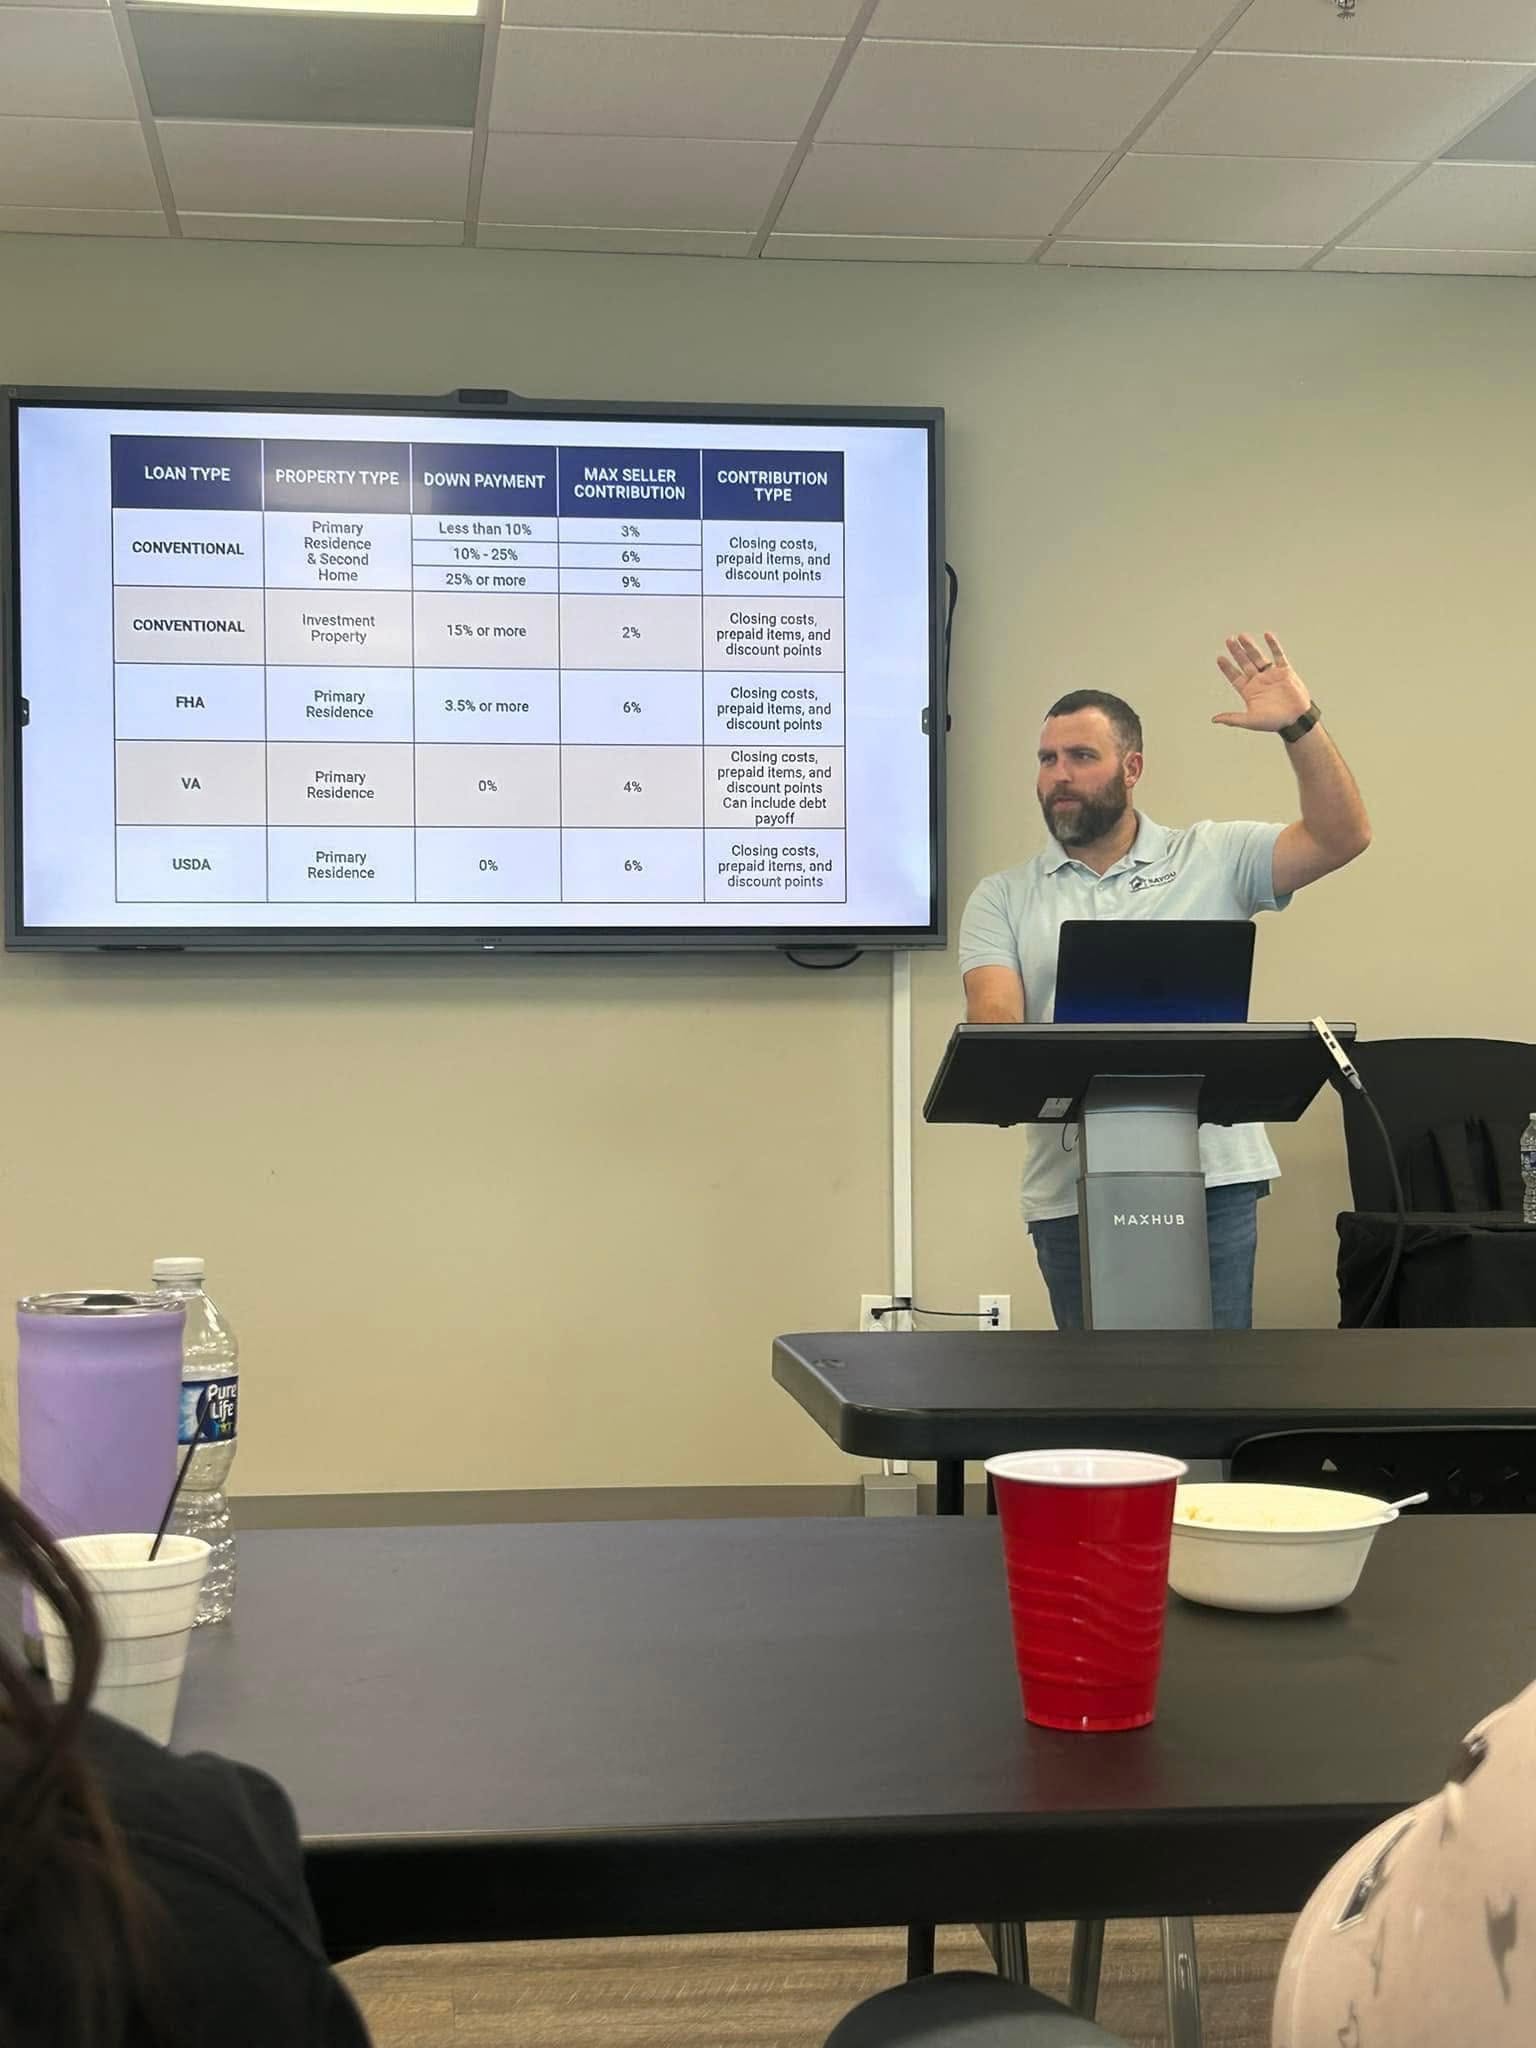

A live first time home buyer class on Zoom, held on Tuesdays. Come with your questions and leave knowing where you stand.
Straight answers on buying, refinancing, and investing.
Wherever you’re buying, Channing shops it across multiple wholesale lenders and finds your best rate. Fifteen minutes gets you a real number instead of a guess, and the soft credit check costs your score nothing.