FHA
Flexible credit, smaller savings
- Down
- 3.5%
- Credit
- 580, or 500 with 10% down
- Upfront Fee
- 1.75%
- Monthly MI
- For life under 10% down
- Seller Help
- Up to 6%
You don’t need to know which loan you want before you start. FHA, VA, USDA, and conventional each fit a different buyer. I’ll run them side by side with your real numbers so you can see which one fits.
A home purchase loan is a mortgage used to buy a home. The main types are FHA, VA, USDA, and conventional loans, each with different down payment, credit, and mortgage insurance rules. The right one depends on your credit, savings, income, service history, and where you're buying.
Every home purchase loan answers the same questions differently: how much you need down, what credit score you need, whether you pay mortgage insurance, and what kind of home you can buy. FHA, VA, and USDA are backed by the government. Conventional loans aren't, and they follow Fannie Mae and Freddie Mac rules.
You'll also choose a term, like a 30 year fixed, a 15 year fixed, or an adjustable rate. The loan type and the term together set your payment, so it's worth comparing a few combinations before you decide.
If you served, start with a VA loan. Zero down and no monthly mortgage insurance is hard to beat. If you're buying outside the core of the city with moderate income and little saved, check USDA next, since it's also zero down.
If your credit is in the 580 to high 600s range or your debt is on the higher side, FHA is usually the best fit with 3.5% down. If your credit is around 700 or higher and you have 5% or more to put down, conventional often costs less, and its mortgage insurance comes off later.
For a second home or a rental, conventional is the standard choice, since the government programs are only for homes you live in. The best way to know for sure is to run your real numbers through two or three options and compare the payments side by side.
The four loans most Lake Charles buyers use, on the numbers that actually change your payment and your cash to close.
Flexible credit, smaller savings
Veterans and service members
Eligible areas, income under the limit
Stronger credit, second homes, investors
My take: don’t pick a loan by its name. Pick it by the payment and what it costs you over the years you’ll actually own the home.
The down payment gets all the attention, but it’s only one of three costs. Here’s the whole picture so nothing surprises you.
Anywhere from $0 to 5% for most buyers, depending on the loan. It can come from checking, savings, a 401k, or a documented gift from family. Cash kept at home can’t be used.
Usually 2 to 5% of the price: title work, lender fees, insurance, taxes, and recording fees. The seller can often cover some or all of it, so ask for it in your offer.
The appraisal, usually about $600 to $700, and your home inspection. With the right loan and a seller who covers closing costs, these can be most of what you bring.
Most purchases close in about 30 to 45 days from contract. Here’s what happens and when.
We review your income, credit, debts, and funds the way an underwriter will, and show you every loan you qualify for. How pre-approval works
Shop in the price range that fits your monthly budget, not just your max approval.
Your offer includes your pre-approval letter and any seller concessions you’re asking for.
We order the appraisal and the underwriter reviews your file. Questions and document requests are a normal part of this.
Once every condition is satisfied and title is ready, we schedule closing. You sign, get your keys, and move in.
What I tell buyers before they start touring homes.
Talk to a lender three to six months out, sooner if your credit needs work. The worst time to find a problem is after you’ve made an offer.
While you save for years, prices keep going up. Compare buying now with what’s available against waiting.
On most loans the seller can cover a big piece of your closing costs. If you don’t ask, you don’t get it.
Being approved for more doesn’t mean you should spend it. Shop at the payment you’re comfortable with.

A home purchase loan is a mortgage used to buy a home. The main types are FHA, VA, USDA, and conventional loans, each with different down payment, credit, and mortgage insurance rules. The right one depends on your credit, savings, income, service history, and where you're buying.
It depends on the loan. VA and USDA need nothing down. Conventional needs 3% for first time buyers and 5% for everyone else. FHA needs 3.5% with a 580 score. Down payment assistance can cover some or all of it on certain loans.
FHA allows 3.5% down at 580, and 500 to 579 with 10% down. Conventional starts at 620, though pricing gets much better in the high 600s. USDA needs about 640 for an automated approval. VA sets no minimum, but lenders usually start around 580 to 620.
Usually about 2 to 5% of the purchase price. That covers things like the appraisal, title work, lender fees, insurance, taxes, and recording fees. On most loans you can ask the seller to pay some or all of them.
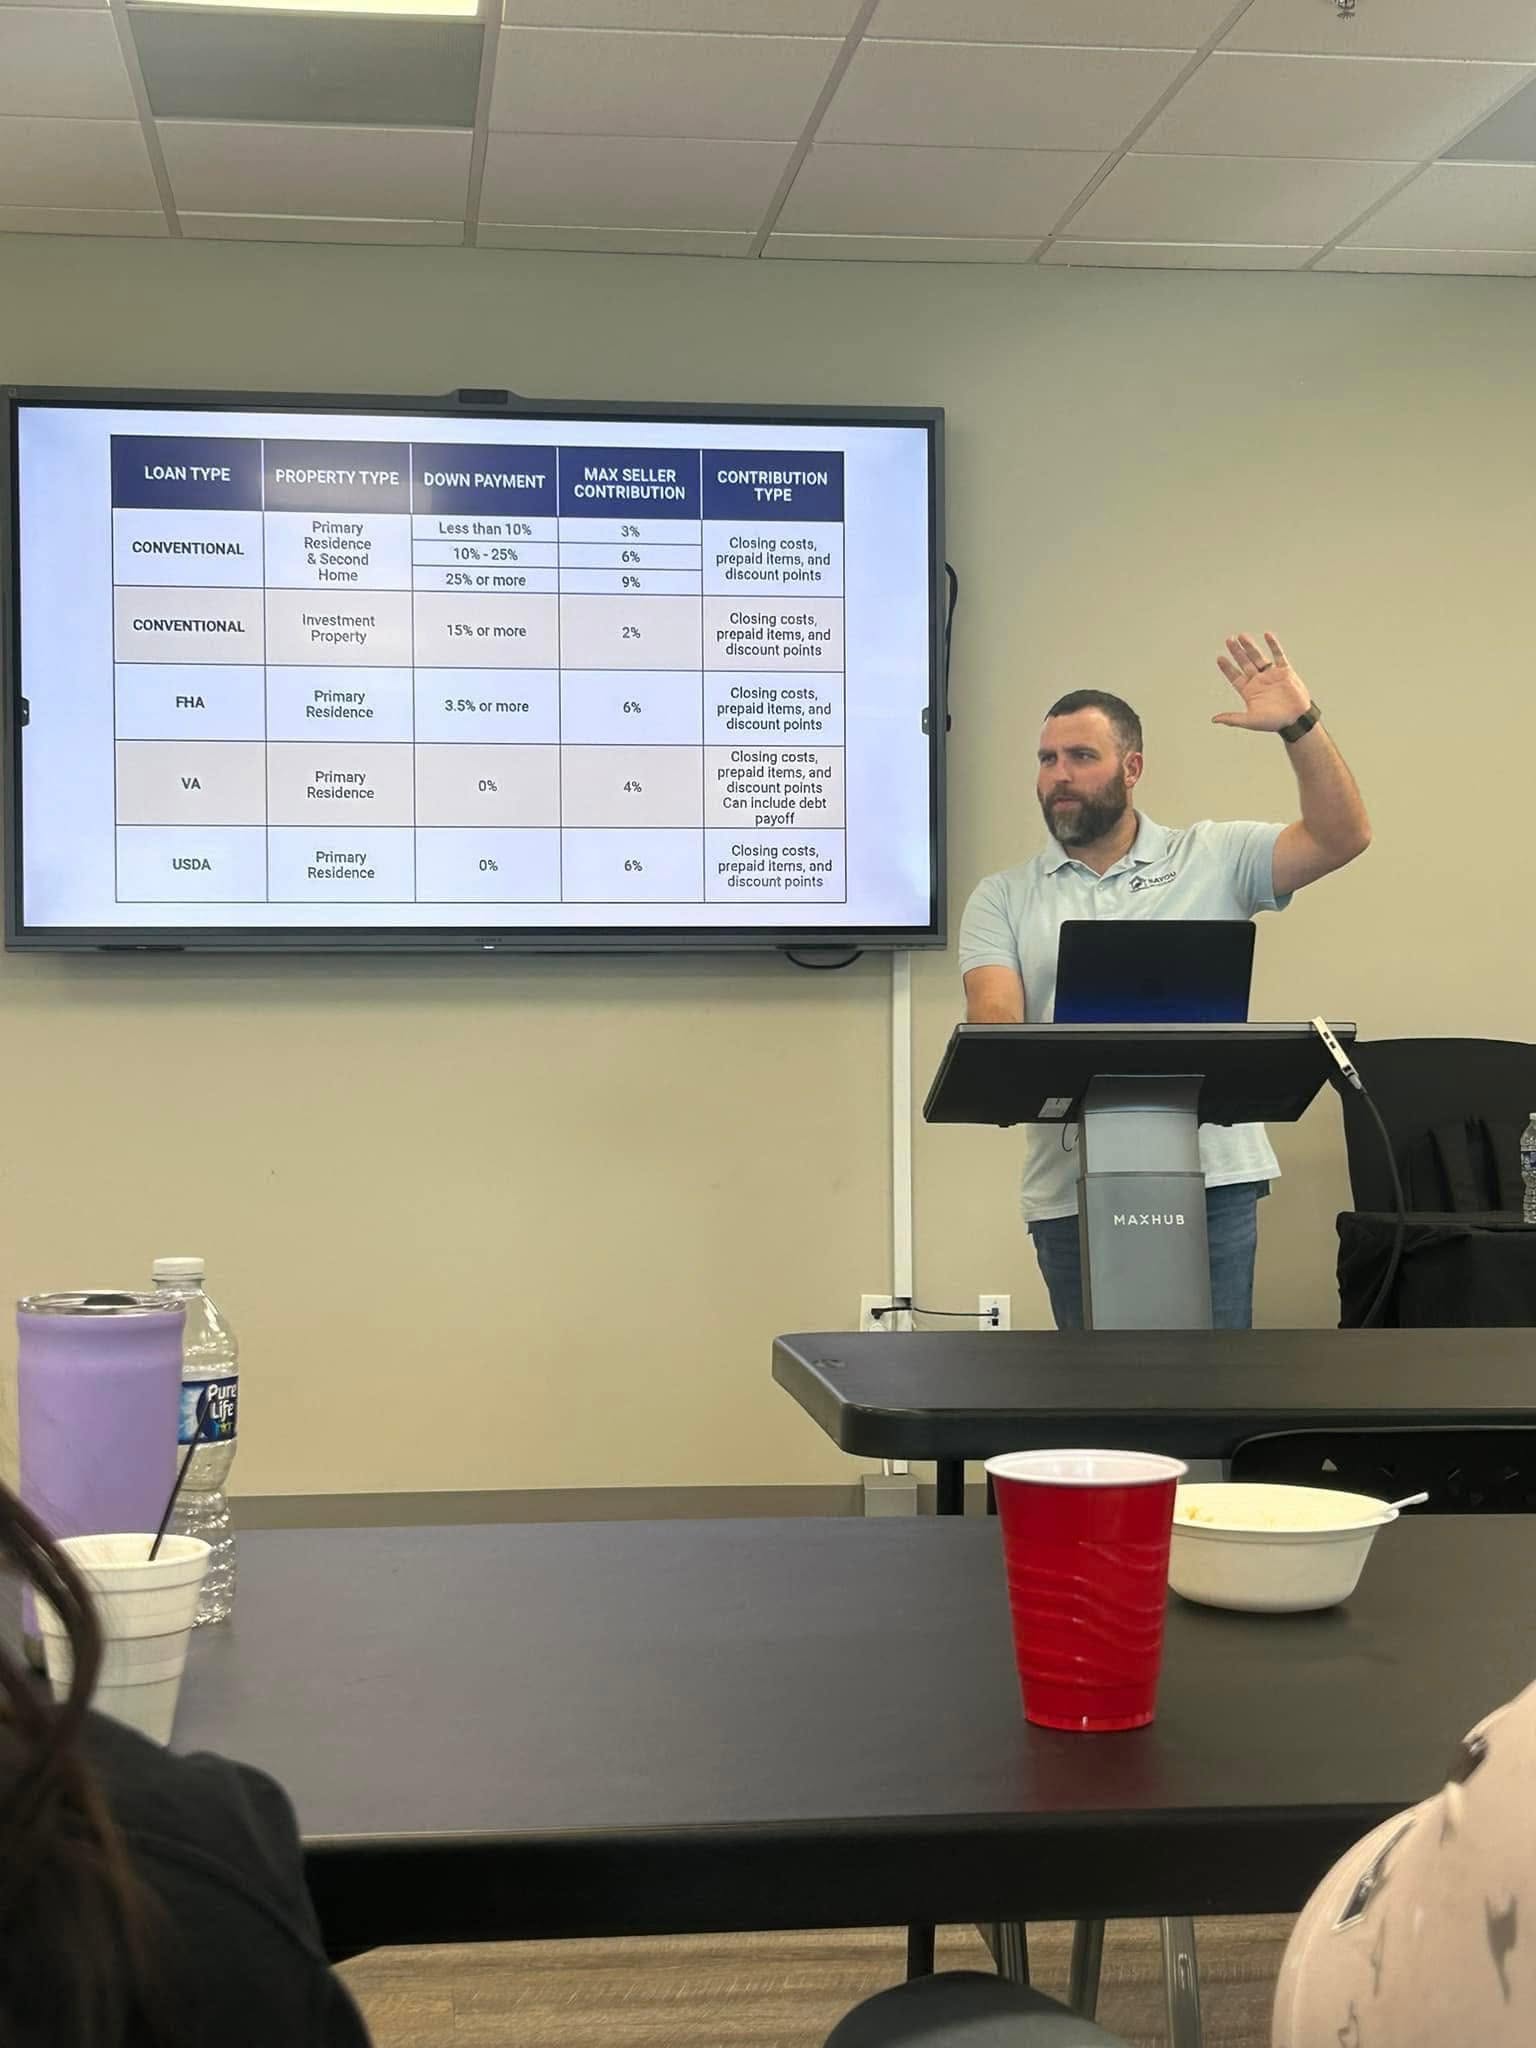
FHA and USDA allow up to 6% of the price. VA allows normal closing costs plus up to 4% in concessions. Conventional allows up to 3% when you put less than 10% down. Ask for it in your offer.
Typically the appraisal and the home inspection. The appraisal usually runs about $600 to $700 depending on the market. Everything else is usually settled at closing.
Most purchases close in about 30 to 45 days from contract. USDA loans add a review by USDA after the lender approves the file, so we plan USDA contracts for 30 to 45 days to be safe.
Before you make an offer, yes. Sellers usually won't accept an offer without a pre-approval letter. Ideally you start three to six months before you plan to buy.
For most buyers, no. While you save for years, prices keep rising, so the target keeps moving. Compare buying now with what's available against waiting, and factor in appreciation.
Yes. Conventional loans work for second homes with 10% down and investment properties starting around 15 to 20% down. DSCR loans qualify investment properties on the rent instead of your income. FHA, VA, and USDA are for the home you live in.
Often yes. Depending on your income and equity, you may qualify to carry both payments, or a bridge loan can use the equity in your current home to fund the next purchase.
Whether it’s your first home, a second home, or a rental, start here.
The five steps to a pre-approval that holds up when you find the house.
Learn More BuyEvery program that can get you into your first home, compared side by side.
Learn More BuyHelp covering your down payment, usually paired with an FHA loan.
Learn More BuyFinancing for a vacation home or second place you’ll use part of the year.
Learn More InvestBuy rental property qualified on the rent, not your personal income.
Learn More BuyFor loan amounts above the $832,750 conforming limit.
Learn MoreFifteen minutes gets you a real number instead of a guess, and the soft credit check costs your score nothing.
Real Closings
Real families we have helped get from pre-approval to keys in hand.
Pick one and I'll match you to the right loan, the real numbers, and the next step. Takes about 60 seconds — no credit pull, no obligation.