Lake Charles
First Time Home Buyer Loans
Almost everything written for first-time buyers is a loan explainer wearing a different hat. This is not that. Your loan options are on their own pages. This page is about the things that only matter the first time: whether you qualify as a first-time buyer at all, what cash you actually need, and the specific mistakes that cost people money around here.
You May Qualify Already
What Actually Counts As
A First Time Buyer
This is the single most misunderstood definition in the business, and it costs people assistance money they were entitled to. You do not have to have never owned a home. For almost every program that matters, a first-time buyer is anyone who has not owned a principal residence in the past three years.
Read that again if you have owned before. It means a lot of people in their thirties and forties around Lake Charles qualify and have no idea.
- Sold a house four years ago and rented since? You qualify again
- Divorced and the house went to your ex more than three years ago? Usually yes
- Owned only a rental, never lived in it? It was not your principal residence
- Inherited a property you never occupied? Ask — it often does not disqualify you
If any of those sound like you, say so when we talk. It is a thirty-second question that occasionally unlocks thousands of dollars.
The Real Number
What Cash You Actually
Need To Close
Everybody fixates on the down payment. The down payment is one of four numbers, and it is frequently not the biggest one. Here is the whole picture on a $225,000 purchase in Lake Charles — roughly mid-market for this area — using an FHA loan at 3.5% down.
| What You Pay For | Rough Cost | What It Is |
|---|---|---|
| Down payment | $7,875 | 3.5% of the purchase price. The part everyone knows about. |
| Closing costs | $4,500 to $6,750 | Roughly 2 to 3%. Lender fees, title work, the notary, parish recording. |
| Prepaids and escrow | $3,500 to $5,500 | A year of homeowner's insurance up front, plus several months of taxes and insurance to open the escrow account. |
| Earnest money | $1,000 to $2,500 | Paid when your offer is accepted, then credited back to you at closing. |
| Realistic total | $15,000 to $20,000 | Before any seller credit or assistance. |
Estimates for shape, not a quote — your actual figures depend on the property, the lender and the date you close. But the point holds: the gap between the $7,875 people budget for and the $16,000 the file actually needs is where first-time purchases fall apart. Now the good news, which is that both of the last two columns are negotiable or fundable.
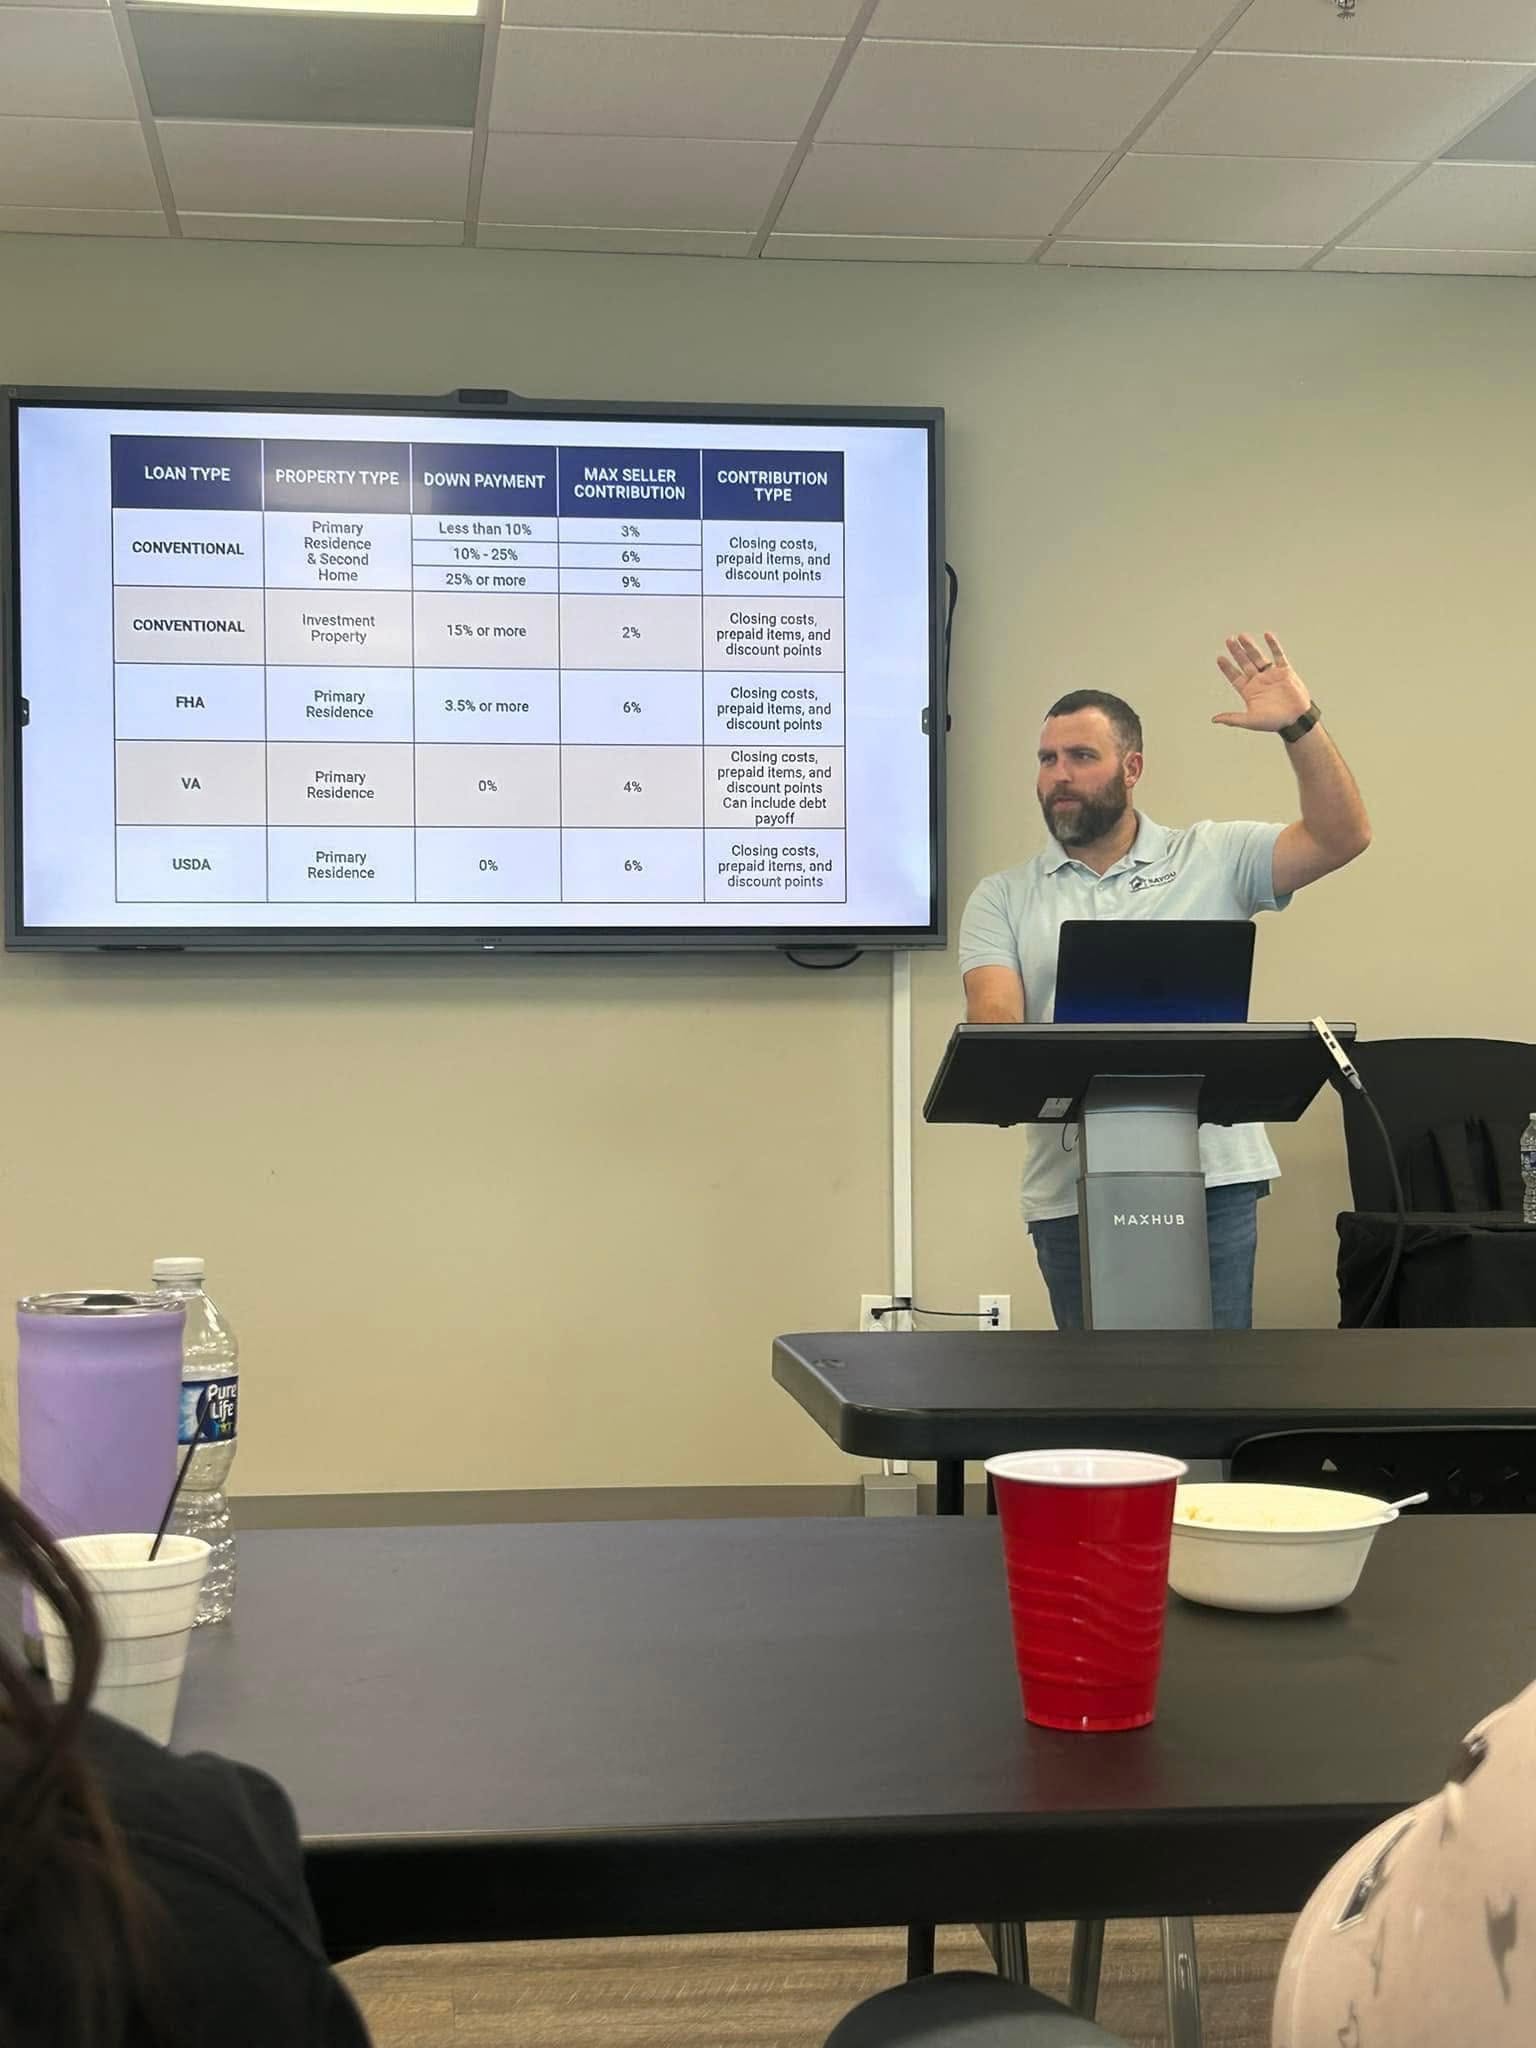
Seller credits
A seller can contribute toward your closing costs. On a house that has been sitting, this is often easier to get than a price reduction, and it helps you more.
Lender credits
Take a slightly higher rate and the lender covers some costs. Sometimes smart, sometimes not — it depends how long you will keep the loan.
Gift funds
Family can gift the entire down payment on FHA and conventional. It needs a gift letter and a clean paper trail, not cash in an envelope.
Assistance programs
Louisiana Housing Corporation programs can cover down payment and sometimes closing costs, subject to income and price limits.
Zero-down loans
USDA just outside the city limits, or VA if you served. Both remove the down payment line entirely.
Escrow timing
Closing right after a tax bill is paid means fewer months to fund up front. Worth a conversation about your closing date.
Narrowing It
Which Loan Fits
A First Purchase
Four programs do most of the work for first-time buyers here. Each has its own page with the detail; this is only the routing, so you know which one to read.
| Program | Down | Best When |
|---|---|---|
| FHA | 3.5% | Your credit is under about 680, or you have a recent credit event. |
| USDA | $0 | You are buying in Moss Bluff, Sulphur, Westlake or similar — not inside the city limits. |
| VA | $0 | You or your spouse served. Beats everything else here on cost. |
| Conventional | 3% | Your credit is above about 700 and you want the mortgage insurance to end. |
The ranking flips on credit score and address, which is why I will not tell you which one you want before seeing either. What I will tell you is that guessing wrong here costs more than any other decision in the process.
Learn These For Free
The Mistakes That Cost
First Time Buyers The Most
Every one of these I have watched happen to someone buying their first house. None of them are about being bad with money. They are about not knowing a rule that nobody thought to mention.
Buying a car mid-process
The most expensive mistake on this list. A new car payment between pre-approval and closing can re-qualify you out of your own loan. Buy nothing on credit until you have keys.
Moving money around
Large deposits underwriting cannot trace will stall your file. Shuffling savings between accounts to "look organised" creates work, not clarity. Leave it where it sits.
Shopping without pre-approval
You will fall for a house you cannot buy, or lose one to a buyer whose paperwork was ready. Start with pre-approval, not with listings.
Skipping the inspection
An appraisal is not an inspection. The appraiser is protecting the lender's collateral, not telling you the water heater is failing.
Budgeting to the maximum
Your approval is a ceiling, not a recommendation. The payment that makes underwriting comfortable can still make your life tight.
Changing jobs
Even for more money. Underwriting wants stability, and a start date after closing is far safer than one before it. Tell me first.
After You Have Keys
Your First Twelve Months
As An Owner
Nobody writes this part, because most of the industry stops caring once the loan funds. These are the four things that matter in year one, and two of them can save you real money.
File your homestead exemption
Louisiana exempts a portion of your home's value from property tax, but you have to file with the Calcasieu Parish assessor. It is not automatic. Do it in your first year.
Expect an escrow adjustment
Your first-year escrow is an estimate. When the real tax and insurance bills land, the payment adjusts. A change is normal, not a mistake.
Build the repair fund
You no longer call a landlord. A modest monthly set-aside turns a failed water heater into an errand instead of a crisis.
Watch for the refinance window
If rates drop or your credit improves, a refinance may be worth it. On FHA, getting out of mortgage insurance is often worth more than the rate itself.
First-time buyers get the least patient service in this business, which is backwards. Working with a Lake Charles mortgage broker means the person answering your questions is the same one placing your loan.
Questions I Get Weekly
Lake Charles First Time
Buyer Questions
Start Here
Find Out Your Real Number First
A soft credit check, no obligation, and a straight answer about what you can afford and what it will cost you to close.
Where To Find Us
Our Lake Charles Office
Mortgages by Channing
Mortgage Broker · Lake Charles, LA
- Address
- 113 Williamsburg Street
Lake Charles, LA 70605 - Phone
- 337-476-2623
- channing@mortgagesbychanning.com
- NMLS
- Company 1660690 · Channing Moore 1235512
Hours
Central Time
- Monday – Friday8 AM – 5 PM
- SaturdayClosed
- SundayClosed
Calls and applications come through outside office hours too — Channing answers them the next morning.
Lake Charles Mortgage Options
Lake Charles
Home Loan Programs
One broker, every program below. If you are not sure which one fits, start with pre-approval and we will narrow it from your actual numbers.
Buying a Home
- Home Purchase Loans
- Mortgage Pre-Approval
- First Time Home Buyer Loans
- Down Payment Assistance
- Second Home Loans
Government Loans
Conventional & Fixed Rate
- Conventional Loans
- 30 Year Fixed Rate Mortgage
- 15 Year Fixed Rate Mortgage
- Adjustable Rate Mortgage
Investors & Self-Employed
- DSCR Loans
- Bank Statement Loans
- Non QM Loans
Refinancing
- Mortgage Refinance
- Cash Out Refinance
- FHA Streamline Refinance
- VA IRRRL
- USDA Streamline Refinance
Equity & Bridge
- HELOC
- Home Equity Loans
- Bridge Loans
The Application
Apply From Your Phone In Fifteen Minutes
You have never done this before, so here is exactly what it looks like. The whole application runs on your phone, and it reaches me the minute you submit it.
- Starts with a soft credit check, so your score is never touched
- We check which down payment assistance programs you qualify for
- Upload documents with your phone camera, no scanner needed
- You hear back from Channing, not from a call center queue
If the numbers say wait, I'll tell you that too, and then we make a plan to fix whatever is in the way.
Complete Your Application
Five short steps. Most people finish in about fifteen minutes.
- Tell us what you're looking for
- We check assistance programs
- Upload your documents
Your pre-approval letter is ready. I sent it to your email and to your agent.
Got your application. I'm reviewing it now and will call you this afternoon.
Real Closings
Real Clients.
Real Closings.
Real families we have helped get from pre-approval to keys in hand.
Buy Your First House
In Lake Charles
No question is too basic. That is the whole job, and it is the part I like most.